Why can’t any lender promise “no refusal”?
Because a licensed payday lender isn’t allowed to lend to just anyone. Provincial law sets the most it can lend you, stops it lending while you already owe it, and expects it to check who you are and what you earn. A lender that skipped all of that wouldn’t keep its licence for long.
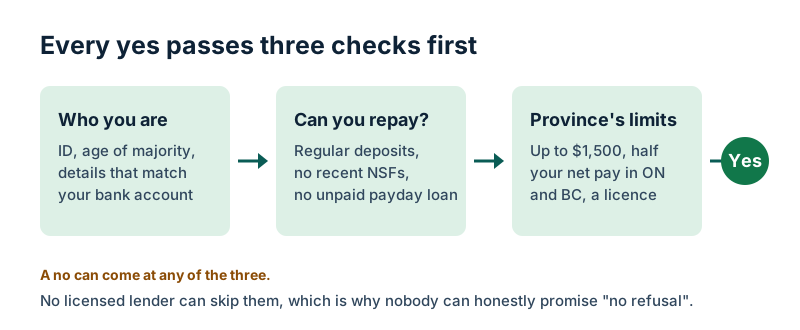
So “no refusal” is a marketing line, not a product. It shows up in two places. Brokers use it to collect your application and sell it on. Scammers use it to set up a request for a fee before the loan arrives. New Brunswick’s Financial and Consumer Services Commission lists guaranteed loans for people with bad credit among the warning signs of a loan scam.
What you can get honestly is a fast decision, and good odds if you meet the basics.
Would a payday lender approve me?
Tick what’s true for you. Anything you leave unticked shows what usually causes a refusal and what you can do about it.
What usually stops a yes, and what to do about it
- Lenders can't sign a loan contract with someone under the age of majority. There's no workaround here.
- Without regular deposits a payday lender has nothing to schedule repayment against. Pension, EI and most benefits count as income at many lenders, so mention them.
- Many lenders want to see at least a few months of history. If your account is new, a lender that accepts PDF statements from your old account may still work, or ask your bank for a small overdraft instead.
- Recent NSFs are one of the most common reasons for a no. Wait until you have a clean month or two, and call the creditor behind the bounced payment to set up a plan.
- In Ontario, Alberta and British Columbia a lender can't give you a new payday loan while one is still outstanding. Repay it first, or ask about an extended payment plan.
- Ontario and BC cap a payday loan at 50% of your net pay for the loan period, and lenders elsewhere use similar limits. Ask for less, and the yes often comes back.
- A lender that can't match your details to your ID or bank account will refuse, or stall until it can. Use your legal name and the address on your bank statements.
- Quebec, Yukon, the Northwest Territories and Nunavut have no payday licence, so licensed payday lenders won't lend there. Look at cash advance apps, instalment lenders or your caisse or credit union.
This check runs in your browser and isn’t saved or sent anywhere. Ticking every box doesn’t guarantee approval; each lender makes its own decision.
Why do payday loan applications get refused?
Refusals almost always come down to one of these, and none of them is your credit score alone.
- Your bank account tells a different story
- Bounced payments, an overdraft that’s always maxed out, or several payday lenders’ withdrawals in the last month. Lenders read your recent statements closely because that’s where repayment will come from.
- You already owe a payday lender
- In Ontario, Alberta and BC, a lender can’t give you a new payday loan until your current one is paid. See how many payday loans you can have.
- You asked for too much
- The legal maximum is $1,500 in every province that licenses payday lenders, and Ontario and BC also cap a loan at half your net pay for the period. A first-time borrower may be offered less than the cap.
- The lender couldn’t verify you
- A name spelled differently from your ID, an old address, or a phone number that doesn’t work. The fix is simple: use your legal details exactly as they appear on your bank statements.
- The lender doesn’t serve where you live
- A payday lender needs a licence in your province, not just somewhere in Canada. Each lender profile lists where it’s licensed.
How fast is online approval?
Fast, on a weekday. Here’s what typically happens depending on when you apply:
| When you apply | Usual decision | Money, once you sign |
|---|---|---|
| Weekday morning | Within an hour or two | Often the same day by Interac e-Transfer |
| Weekday evening | Next morning, unless the lender reviews late | Next business day |
| Weekend or holiday | Monday, at most lenders | Monday or Tuesday |
Two things speed it up: having a recent bank statement or pay stub ready, and answering the lender’s verification call or email straight away. The table below shows each payday lender’s published speed, the most it lends, and what it says about credit checks.
Applications go through our partner Loans Canada, which may match you with this or other lenders. Koke may be paid for referrals. Lenders decide approval, cost and terms.
| Lender | Speed | Up to | Credit check | Licensed in |
|---|---|---|---|---|
| Blue Copper Capital | Same day | $1,500 | Says bad credit won't automatically lead to rejection; instalment and line-of-credit repayments are reported to credit bureaus | AB |
| Cash 4 You | Same day | $1,500 | Not stated | BC, ON |
| Cashco Financial | Same day | $1,500 | Not stated | AB, BC, SK |
| Focus Cash Loans | Same day | $1,500 | Says it does not run credit checks, though its terms allow it to request bureau information | AB, BC, ON |
| GoDay | Same day | $1,500 | GoDay says it may run a credit check and also weighs income and existing debts | AB, BC, MB, NB, NS, ON, PE, SK |
| Instant Payday Canada | Same day | $1,500 | Not stated | BC, ON, SK |
| Loan Express | Same day | $1,500 | Not stated | AB, BC, MB, NB, NL, NS, ON, SK |
| Money Mart | Same day | $1,500 | Not stated | AB, BC, MB, NS, ON, SK |
| Mr. Payday | Same day | $1,500 | Not stated | AB, BC, ON |
| My Canada Payday | Same day | $1,500 | Published reviews say decisions are based on your bank account activity rather than your credit history | AB, BC, MB, NS, ON, SK |
| Pay2Day | Same day | $1,500 | No credit check stated in published reviews | AB, BC, NS, ON |
| Speedy Cash | Same day | $1,500 | No credit check required, as stated in published reviews | AB, BC, MB, NB, NL, NS, ON, SK |
| Venue Financial Centres | Same day | $1,500 | No credit check required, according to published reviews | AB, BC, SK |
| Wagepay | Same day | $1,500 | Not stated | AB, BC, ON |
| iCash | Same day | $1,500 | Hard credit check on the first loan only, according to published reviews | AB, BC, MB, NB, NS, ON, PE |
| Cash Money | Next business day | $1,500 | Not stated | AB, BC, MB, NB, NL, NS, ON, SK |
From each lender’s own site and published reviews, checked on its profile date. Speed assumes approval during business hours. Every lender still sets its own approval rules, and your province’s limits apply.
Want the money to land in minutes once you’re approved? Here’s which lenders pay by e-Transfer and how fast.
What should I do if I’m refused?
- Ask why. Many lenders will tell you the main reason if you call or email. It’s the fastest way to know whether to try again or try something else.
- Don’t apply everywhere at once. Each application shares your details with another company and may add a credit inquiry. Two refusals in a row is a signal to stop and fix the cause.
- Check your credit report. Equifax and TransUnion both let you see your report for free online. Mistakes happen, and you can ask for them to be corrected.
- Fix what you can. Clear a bounced payment, repay an existing payday loan, ask for a smaller amount, or wait until your account has a few clean months.
- Look at a different kind of help. If the refusal was because you’re already stretched, another loan may not be the answer. Read what to do if you can’t repay a payday loan, or talk to a free non-profit credit counsellor.
Who has better odds of a fast yes?
Lenders care more about steady deposits than about your job title. Some situations raise questions you can answer in advance:
- Poor or thin credit. Often fine with payday lenders, many of which don’t check the bureaus. See lenders that skip a hard credit check and payday loans with bad credit.
- On benefits or a pension. Many lenders accept EI, CPP, OAS and disability payments as income. Our page on borrowing on benefits explains what each type needs.
- Self-employed or gig work. Expect to show a few months of bank statements with regular deposits, since there’s no pay stub.
- New to Canada. A new bank account is the usual hurdle. Wait for a couple of months of deposits, or start with your bank’s own small credit products.
What are the rules where I live?
Nine provinces license payday lenders, and all nine cap the cost at $14 per $100 and the loan at $1,500. Cooling-off periods, the longest term and the half-your-pay limit differ, so check yours: Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island and Saskatchewan. The rules by province page puts them all side by side.
Quebec, Yukon, the Northwest Territories and Nunavut don’t license payday lenders, and no lender there may charge more than 35% a year. Your fastest honest options are a cash advance app such as KOHO, which doesn’t run a credit check, or a small loan from your caisse or credit union.
Is there a faster yes than a payday loan?
Sometimes. If your bank offers overdraft protection, it’s already approved and costs far less. KOHO’s Cover advances up to $500 in its app with no credit check, for a monthly fee. Your employer may advance part of your pay. And for anything over $1,500, an instalment lender or a credit union such as Libro or FirstOntario will take a little longer to decide but charge much less. More ideas are on the alternatives to payday loans page, and you can price any option in the payday loan calculator.
Ready to apply?
Koke’s application takes about three minutes. Our matching partner looks for lenders whose rules fit your answers, so you’re not applying blind. The lender makes the decision and shows you the full cost before you sign.
Start my application Compare lenders
Common questions
Is there any payday lender that never refuses?
No. A licensed lender that approved everyone would be breaking provincial rules on loan size and repeat borrowing, and it would quickly go out of business. A website that says it never refuses is either a broker passing you on, or a scam setting up a request for an upfront fee.
Does being refused for a payday loan hurt my credit score?
The refusal itself isn’t recorded on your credit report. If the lender ran a hard credit check, that inquiry is, and several in a short time can lower your score a little. Many payday lenders don’t check the credit bureaus at all, so a refusal from them leaves no trace on your file.
How many payday loan applications is too many?
If you’ve been turned down twice, stop and find out why before trying again. Each new application shares your details with another company and may add a credit inquiry, and lenders can often see that you’re applying everywhere. Fix the reason for the refusal, or look at an alternative.
Why was I refused when I have a full-time job?
A job is only one part of the decision. The most common other reasons are bounced payments in your bank account, an unpaid payday loan, asking for more than half your next paycheque in Ontario or BC, a new bank account, or details that don’t match your ID.
How soon can I reapply after a refusal?
There’s no legal waiting period. Some lenders ask you to wait about 30 days before reapplying with them. Reapplying the next day with nothing changed usually gets the same answer, so fix the reason first, whether that’s clearing an NSF, repaying an existing loan or asking for less.
Do payday lenders approve people on EI, CPP or disability?
Many do, because they look for regular deposits rather than a paycheque. In Ontario, a payday lender can accept proof of Ontario Works or ODSP payments. Each lender sets its own list of accepted income, so check before you apply.
Can I get approved on a weekend?
You can apply any time, and a few lenders review applications seven days a week. Most approve only during business hours, so a Saturday application is often decided and paid on Monday. Check each lender’s review hours on its Koke profile.
Does applying through Koke make approval more likely?
Not directly. Koke sends your answers to a matching partner that looks for lenders whose rules fit you, which can save you from applying to lenders that would refuse you anyway. The lender still makes the decision, and nobody can promise a yes.