What does “no credit check” actually mean?
It means the lender doesn’t pull your file from Canada’s two credit bureaus, Equifax and TransUnion, before deciding. That’s it. It doesn’t mean nobody looks at anything, and it doesn’t mean everyone gets approved. Lenders use a few terms that sound alike but work differently:
- Hard credit check
- The lender requests your full credit file because you’ve formally applied. It’s recorded on your report, other lenders can see it, and it can nudge your score down a little.
- Soft credit check
- A lighter look, often used to show you a rate before you commit. It doesn’t affect your score, and other lenders can’t see it.
- No credit check stated
- The lender says it doesn’t use the credit bureaus at all and decides based on your income and bank account. Many licensed payday lenders and cash advance apps work this way.
- Bank verification
- Instead of your score, the lender reviews a few months of your bank activity, either from statements you send or through a secure bank-data service you sign into yourself. Never type your banking password into an email, a text or a form a person sent you.
Which lenders don’t run a hard credit check?
These lenders on Koke either say they don’t use the credit bureaus or show you a quote with a soft check first. The table is built straight from each lender’s profile, so it changes when a lender changes its policy. Payday lenders also need a licence in your province; open a profile to see where each one is licensed and how to check it.
Applications go through our partner Loans Canada, which may match you with this or other lenders. Koke may be paid for referrals. Lenders decide approval, cost and terms.
Lenders that say they don't run a credit check
| Lender | Product | What they say about credit | Up to | Serves |
|---|---|---|---|---|
| Focus Cash Loans | Payday loan | Says it does not run credit checks, though its terms allow it to request bureau information | $1,500 | AB, BC, ON |
| My Canada Payday | Payday loan | Published reviews say decisions are based on your bank account activity rather than your credit history | $1,500 | AB, BC, MB, NS, ON, SK |
| Pay2Day | Payday loan | No credit check stated in published reviews | $1,500 | AB, BC, NS, ON |
| Speedy Cash | Payday loan | No credit check required, as stated in published reviews | $1,500 | AB, BC, MB, NB, NL, NS, ON, SK |
| Venue Financial Centres | Payday loan | No credit check required, according to published reviews | $1,500 | AB, BC, SK |
| KOHO | Cash advance | KOHO says it doesn't run a credit check for Cover; a balance left unpaid for three months or more may be reported to the credit bureaus | $500 | All provinces |
Lenders that quote you with a soft check first
| Lender | Product | What they say about credit | Up to | Serves |
|---|---|---|---|---|
| Fairstone | Instalment loan | The initial quote is a soft check that doesn't affect your score; proceeding involves a full credit check | $25,000 | AB, BC, MB, NB, NL, NS, ON, PE, SK |
| Fig | Instalment loan | Soft check to see your offer; a hard check only if you accept and complete the application | $35,000 | All provinces |
| LendDirect | Line of credit | Pre-approval is advertised as no impact to your credit; a full application needs consent to pull your credit report | $10,000 | AB, BC, MB, NB, NL, NS, ON, SK |
| Mogo | Line of credit | Soft Equifax check for pre-approval; a hard check follows when you submit the full application | $5,000 | AB, BC, MB, NB, NL, NS, ON, PE |
Taken from each lender’s own site and published reviews, checked on the date shown on its profile. A lender can change its checks at any time, and every one of them still confirms your identity, income and bank account. Lenders not listed here run a full credit check or don’t say.
Notice what sits in each group. The no-check side is mostly payday lenders capped at $1,500, plus KOHO’s Cover advance of up to $500. The soft-check side is instalment lenders and lines of credit such as Fig, Fairstone, Mogo and LendDirect: the soft check only gets you a quote, and they run a full credit check before sending money. Bigger amounts always come with a closer look.
Is instant approval real?
Fast decisions are real. Instant approval for everyone isn’t. A licensed lender has to confirm who you are and that you can repay before it lends, and in most provinces it has to give you a written agreement first. New Brunswick’s Financial and Consumer Services Commission lists “they offer instant approvals” right beside “they ask you to send money upfront” in its warning signs of a loan scam.
Here’s what a genuine online application looks like from start to money in your account:
- The form, about 5 to 10 minutes. Your name, address, income, pay dates and bank details.
- The decision, a few minutes to a business day. Some lenders decide automatically within minutes; others have a person review your file. Either way, most approve only during business hours.
- The agreement. You get the contract showing the amount, the total cost in dollars and the due dates. Read it before you sign. In Ontario, Alberta and British Columbia you can still cancel a payday loan for free within two business days of signing.
- The money, often within the hour. Most online lenders send it by Interac e-Transfer once you’ve signed. See which lenders pay by e-Transfer and how fast.
So a weekday morning application can be money in your account by lunch. A Friday-night one may wait until Monday. Anyone who promises otherwise, or says approval is guaranteed, is telling you what you want to hear.
What will a lender check instead of my credit score?
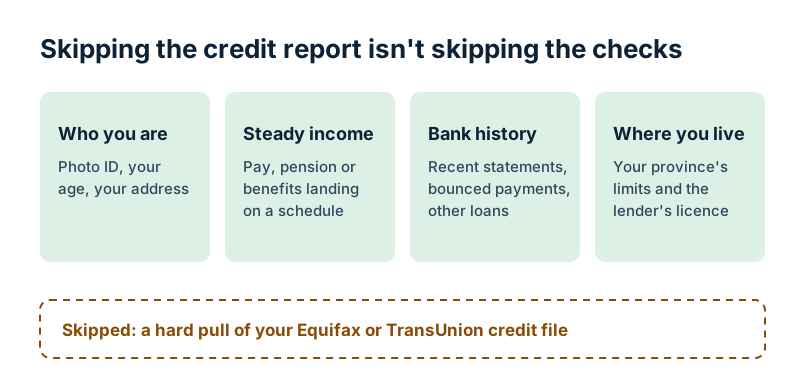
Expect to be asked for most of these, whichever province you live in:
- Your age and identity. You must be the age of majority in your province, 18 or 19 depending on where you live.
- Regular income. A paycheque, pension or regular government benefits. In Ontario, a payday lender can accept proof of Ontario Works or ODSP payments if you’re not working.
- An active chequing account that your income goes into, usually open for a few months.
- Your recent bank activity. Bounced payments and other payday loans count against you more than an old credit score does.
- Your existing payday loans. Ontario lenders can’t give you a new payday loan until seven days after you’ve repaid the last one, and can’t lend more than half your net pay.
If your credit is the reason you’re looking here, our page on payday loans and bad credit goes further, and borrowing on benefits covers EI, CPP, disability and child benefits.
What does a loan without a credit check cost?
Skipping the credit check doesn’t make a loan cheaper; usually the opposite. Here’s what $500 costs with the main options:
| Option | Credit check | Cost on $500 | Typical speed |
|---|---|---|---|
| Licensed payday loan | Usually none | Up to $70, repaid in one or two paydays | Same day once approved |
| Cash advance app (KOHO Cover) | None | No interest; a monthly subscription from $2 | Instant, inside the app |
| Instalment loan at 35% a year | Soft quote, then full check | About $100 in interest over 12 months | One to two business days |
| Credit union personal loan | Full check | Usually far less; rates from about 6% to 9% | A few days |
The $70 payday figure is the legal maximum of $14 per $100, which applies in every province that licenses payday lenders. It looks small next to $100, but it’s charged for weeks, not a year. Borrow $500 for two weeks at $14 per $100 and the yearly rate works out to about 365%. Other consumer loans are capped at 35% a year by the federal criminal interest rate. Try your own numbers in the payday loan calculator or put lenders side by side on the compare page.
How do I spot a fake “no credit check, instant approval” lender?
Loan scams target exactly this search. The Canadian Anti-Fraud Centre and New Brunswick’s regulator describe the same pattern: a quick “approval”, then a request for money before the loan arrives. Walk away if a lender:
- asks for a fee, “insurance”, a “deposit” or a first payment before you receive anything, by e-Transfer, gift card or crypto. In most provinces an upfront loan fee is illegal;
- guarantees approval whatever your credit or income;
- contacts you first, by text, social media or a call you didn’t ask for;
- won’t show a provincial licence number, or the number isn’t on the regulator’s register. Here’s how to check a payday lender’s licence;
- wants your online banking password, your SIN by email, or a photo of your bank card.
If you’ve already paid one, contact your bank straight away and report it to the Canadian Anti-Fraud Centre at 1-888-495-8501.
What are the limits where I live?
Nine provinces license payday lenders and cap them at $14 per $100 and $1,500 per loan. The details, such as the longest term and how long you have to cancel, differ by province. Tap yours for its full rules and the lenders licensed there.
| Province | Most per $100 | Largest loan | Cancel at no cost | Regulator |
|---|---|---|---|---|
| Alberta | $14 | $1,500 | 2 business days | Service Alberta and Red Tape Reduction |
| British Columbia | $14 | $1,500 | 2 business days | Consumer Protection BC |
| Manitoba | $14 | $1,500 | See province page | Manitoba Consumer Protection Office |
| New Brunswick | $14 | $1,500 | See province page | Financial and Consumer Services Commission (FCNB) |
| Newfoundland and Labrador | $14 | $1,500 | See province page | Digital Government and Service NL |
| Nova Scotia | $14 | $1,500 | See province page | Service Nova Scotia (Consumer Affairs) |
| Ontario | $14 | $1,500 | 2 business days | Ministry of Public and Business Service Delivery and Procurement (Consumer Protection Ontario) |
| Prince Edward Island | $14 | $1,500 | See province page | Island Regulatory and Appeals Commission / Consumer Services |
| Saskatchewan | $14 | $1,500 | See province page | Financial and Consumer Affairs Authority (FCAA) |
Quebec, Yukon, Northwest Territories, Nunavut: no provincial payday-loan licence, so we don’t list payday lenders there. See other options
Full table with example costs on $300, $500 and $1,000, and a free CSV download
In Quebec, Yukon, the Northwest Territories and Nunavut there’s no payday licence, so the federal 35% annual cap applies to every lender. Your choices there are a no-check cash advance app, an instalment lender that serves your area, or your caisse populaire or credit union.
Is there a cheaper way to cover the gap first?
If you have a few days, or your credit is fair rather than poor, these usually cost less than any no-check loan:
- Overdraft protection or a small credit union loan. Libro publishes overdraft of up to $5,000 at 19.49%, and FirstOntario lists unsecured loans from under 8%. Most credit unions across Canada offer something similar.
- A pay advance from your employer, or an earned-wage app your workplace offers.
- A payment arrangement with the bill itself. Utilities, phone companies and landlords often agree to split a bill if you call before it’s due.
- Free help with debt. A non-profit credit counsellor can talk you through options at no cost. If a payday loan is already causing trouble, read what to do if you can’t repay.
More ideas are on our alternatives to payday loans page.
Ready to look at real offers?
Koke’s application takes about three minutes. Koke doesn’t pull your credit report; the lender you’re matched with sets its own checks and shows you the full cost before you sign.
Start my application Browse all lenders
Common questions
Is a no credit check loan the same as a loan with no checks at all?
No. “No credit check” only means the lender doesn’t pull your file from Equifax or TransUnion. It still confirms who you are, that money comes into your account regularly, and that it’s allowed to lend where you live. A lender that checks nothing at all is either not licensed or not real.
Does a soft credit check lower my credit score?
No. A soft check, like the one some lenders use to show you a quote, doesn’t affect your score and isn’t visible to other lenders. A hard check, which happens when you formally apply for most loans and cards, is recorded on your file and can lower your score slightly.
Why do so many websites promise instant approval?
Because it’s what people type into Google when they’re stressed. Licensed lenders have to verify you before they lend, so the honest version is “fast decision”, not “instant approval”. New Brunswick’s financial regulator lists instant approval and guaranteed loans among the warning signs of a loan scam.
Can I get a loan without a credit check on a weekend or at night?
You can usually apply any time, and some lenders review applications seven days a week. Many only approve during business hours, though, so a Saturday-night application may not be funded until Monday. Check the lender’s review hours on its profile before you count on the money.
Will a no credit check loan help me build credit?
Usually not. Most payday lenders and cash advance apps don’t report on-time payments to the credit bureaus. A debt that goes unpaid and is sent to collections can still appear on your report and hurt your score, so a loan that skips the check can damage your credit but rarely improves it.
What can I borrow without a credit check if I live in Quebec or the territories?
Quebec, Yukon, the Northwest Territories and Nunavut don’t license payday lenders, so you won’t find payday loans there on Koke. KOHO’s Cover advance runs no credit check and is offered in Quebec. Otherwise, talk to your caisse populaire or credit union, which will check your credit but usually charges far less.
Does sending an application through Koke check my credit?
Koke itself doesn’t pull your credit report. Your answers go to our matching partner, and the lender you’re matched with sets its own checks. Its page and agreement tell you what it looks at. Read them before you sign anything.
What is the most I can borrow without a hard credit check?
In the nine provinces that license payday lenders, a payday loan can be no more than $1,500, and Ontario also caps it at half your net pay. KOHO’s Cover tops out at $500. Instalment lenders that quote with a soft check lend more, but they run a full credit check before the money is sent.